
Builders Risk Insurance in Fox Chapel, PA
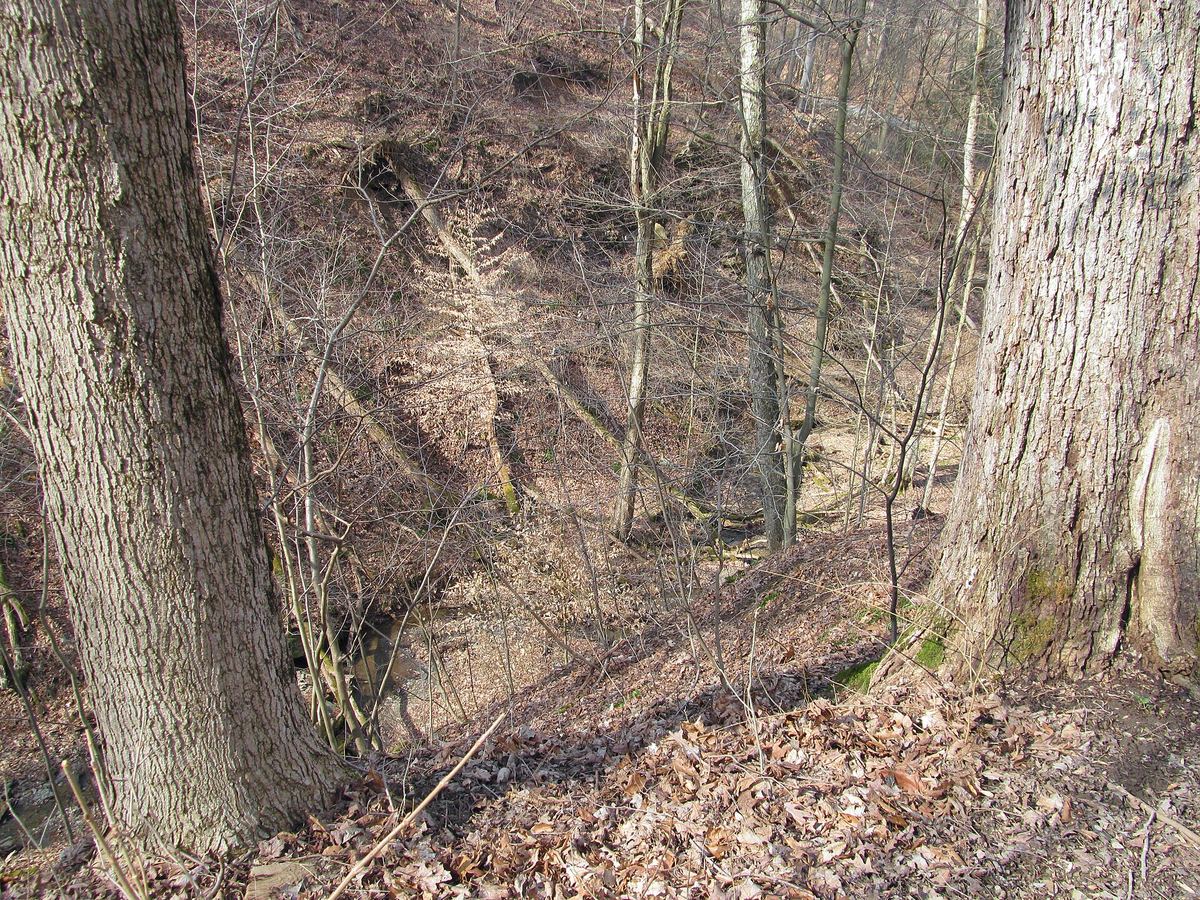
Serving Fox Chapel Owners and Builders
Fox Chapel, northeast of Pittsburgh along the Allegheny River, is known for large homes on wooded lots, winding roads, and ravines. Projects here tend to be custom: a new architect-designed home on a cleared parcel, a full renovation of a mid-century house, or a major addition with a new kitchen wing and garage. Many are financed with a construction loan, which means a bank will have its own insurance requirements before releasing money. Peak Insurance can help Fox Chapel owners and their builders compare builders risk options for eligible projects and line up the documents a lender may ask for.
Our builders risk insurance page explains what course of construction coverage is in general. This page focuses on financed, high-value residential projects in Fox Chapel.
What a construction lender may require
Every lender and loan is different, but the insurance section of a construction loan agreement often addresses:
- Who buys the policy. The owner, the builder, or either, as long as the bank’s interest is protected.
- Limits. Many lenders want the builders risk limit tied to the completed value of the home or the total construction contract, not just the loan amount.
- Mortgagee or loss payee. The bank usually needs to be named on the policy so it is included in any claim payment.
- Deductible caps. Some loans set a maximum deductible.
- Specific perils or endorsements. A lender may ask about theft, wind, or other items, depending on the property.
- Proof before funding. A certificate or binder is often required before the first draw, and the lender may need notice before the policy changes or is canceled.
Read the insurance section of your loan commitment early and send it to us. We can review which available policies may meet those terms. Whether a policy satisfies a lender’s requirements is ultimately the lender’s decision.
Valuing a custom home
Custom construction makes valuation important. Architect-specified windows, stone, millwork, and mechanical systems can raise the cost to rebuild. Underestimating completed value can leave a shortfall after a loss, and some policies have coinsurance or reporting conditions tied to the values you provide. Your builder’s contract and budget are usually the starting point.
Wooded lots and site exposure
Large wooded parcels bring a few extra questions:
- Falling trees onto a framed structure during storms
- Access for fire trucks on long or steep driveways
- Visibility and security on a site set far back from the road
- Drainage on slopes leading into ravines
Wind and falling objects may be addressed by a policy, subject to deductibles and exclusions. Surface water, flood, and earth movement are often excluded or limited. Ask about each one rather than assuming coverage.
Renovating an existing high-value home
If you are renovating instead of building new, the existing house may stay on your homeowners policy, may be included in the builders risk policy, or may need special arrangements during construction, depending on the carriers. Some high-value homeowners carriers have their own rules for major renovations. Talk to your homeowners carrier, and we can help review how a builders risk policy might fit alongside it.
Coordinating with your builder
Custom home builders often carry their own insurance program. Confirm in writing who is providing builders risk, and make sure the builder’s general liability and workers’ compensation are in place. Builders risk generally does not replace those policies, and it usually excludes faulty workmanship or design.
To start a Fox Chapel quote
- Property address and lot description
- New custom home, renovation, or addition
- Contract price, budget, and estimated completed value
- Lender name and the insurance section of the loan documents
- Start date and expected completion
- Builder and architect details
Contact Peak Insurance
Call (855) 449-8552 Monday–Friday, 8:30 AM–4:30 PM, or request a builders risk quote. Peak Insurance is headquartered at 6110 Ridge Ave, Philadelphia, PA 19128, and serves clients across Pennsylvania. Coverage, eligibility, and terms vary by carrier and project; the issued policy and endorsements control.
Get a Builders Risk Quote in Fox Chapel, PA
If the embedded form does not load, open the Peak Insurance form directly or call (855) 449-8552.
Fox Chapel Local References & Nearby Areas
For a general explanation of builders risk, see our main builders risk insurance page and our statewide guide to builders risk insurance in Pennsylvania. For other coverage in this area, visit Peak Insurance in Fox Chapel.
- Other Pennsylvania builders risk pages: Philadelphia, Roxborough, Manayunk, Chestnut Hill, Lafayette Hill, Chester County, Pittsburgh and Sewickley Heights
Frequently Asked Questions
- Does my Fox Chapel construction lender require builders risk?
- Many construction loans do, but requirements vary. Check the insurance section of your loan commitment for limits, deductibles, and how the lender must be named.
- Should the builders risk limit match my loan amount?
- Often lenders ask for a limit based on the completed value or contract price rather than the loan alone. Confirm with your lender and set limits with your builder’s budget in mind.
- Who should buy the policy, me or my builder?
- The construction contract and loan documents usually decide. Get it in writing so there is no gap or duplication.
- Is a tree falling on my unfinished house covered?
- Some policies may address wind and falling objects, subject to terms and deductibles. Ask how a specific policy handles it.
Peak Insurance – Builders Risk Insurance for Fox Chapel, PA
📞 (855) 449-8552
🌠peakinsuranceusa.com
Photo: Cbaile19, CC0. Source: https://commons.wikimedia.org/wiki/File:Ravine,_Fox_Chapel,_2022-03-05,_01.jpg.
