
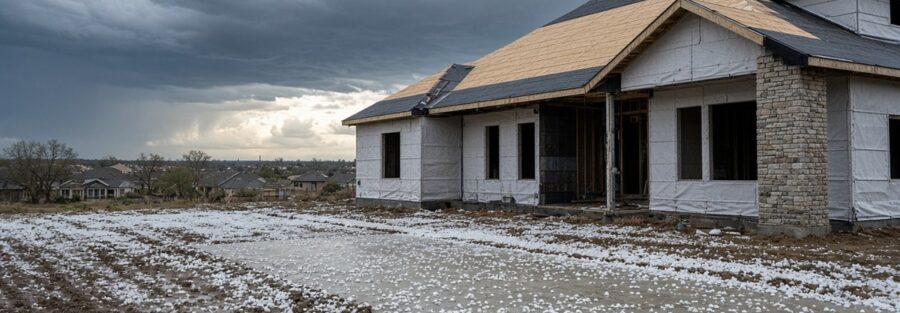
In North Texas, a spring or early-summer afternoon can go from clear to a severe thunderstorm in a short span. Hail can fall on a house that still has roof decking or house wrap instead of a finished roof. That is a hard day to start an insurance conversation. This article looks at what to ask about builder’s risk when a Dallas or Fort Worth project will stand open through storm season. It does not promise that any policy will pay for hail, wind, or water, and it does not set a deductible.
For the product overview, see builder’s risk insurance. For statewide and city pages, see builder’s risk insurance in Texas and builder’s risk insurance in Dallas.
Why an unfinished DFW house is a different risk than a finished one
A completed roof, installed windows, and a closed envelope give a finished house a set of defenses that a framed house does not have. During construction, hail can strike exposed decking, temporary felt or underlayment, window openings, and equipment that has been set in the yard — a condenser, a water heater, a crate of fixtures. Wind can lift loose materials. Heavy rain can enter a structure that is not yet dried in. Builder’s risk exists, in part, for that temporary period. Whether a given loss is covered still depends on the form, the cause, and the conditions in the issued policy.
Dallas-Fort Worth is not unique in having thunderstorms, but the combination of frequent hail reports and a large volume of new residential construction is a practical reason to read the hail and wind wording before the slab is poured, not after the first warning siren.
What to ask about hail and wind on the quote
- Does the form cover hail and wind during construction, and are there separate deductibles for those perils?
- How is an unfinished roof treated? Is there a difference between a dried-in roof and exposed decking?
- Are windows, doors, and skylights covered only after they are installed, or also while they sit in a crate?
- What about HVAC equipment, appliances, or other items staged in the driveway or on a slab?
- Is there a requirement to temporarily protect openings or loose materials when severe weather is forecast?
- If a storm delays the roofer or a key delivery, can the policy term be extended?
- Who reports a loss — the owner, the builder, or either — and how quickly must notice be given?
If the answers are only verbal, ask for them on the quote or in an email from the agent. Two carriers can describe “builder’s risk” in similar headlines and still treat hail on an open roof differently.
After a storm, before the next crew arrives
If hail or wind has already hit the site, safety comes first. Then document what you can without putting anyone at risk: photographs of the roof, the yard, the openings, and the materials, along with the date and approximate time. Save weather reports only as context; the claim, if there is one, will be decided on the policy and the facts of the loss. Call the agent and follow the notice instructions in the policy. Temporary repairs or tarping may be needed to limit further damage. Ask whether the carrier has any rules about those steps, and keep the receipts.
Do not assume that “the builder’s policy will handle it.” Confirm whose policy is in force, what it names, and whether your interest is actually listed.
Schedule slips and a second storm season
A Dallas custom home or a tract house that was supposed to close before peak storm months can still be standing in June. If the original term was written for a shorter calendar, talk to your agent before the expiration date. Extensions are not automatic. A second season of open exposure is exactly the kind of change that should be described to the carrier, not discovered after a loss.
What this article does not do
This article does not forecast hail for any address, does not quote a premium or a deductible, and does not say that builder’s risk will cover a particular storm. Coverage depends on the cause of loss and the policy terms, subject to underwriting and eligibility. Roofing and construction practices should follow the project’s plans and the rules of the jurisdiction that issues the permit. Those rules are not restated here.
Frequently asked questions
Will builder’s risk pay if hail dents a roof that is only partly finished?
It might, or it might not, depending on the form, the deductible, and the condition of the roof at the time of the loss. Ask that question against the actual quote before the roof goes on, and again if the schedule changes.
The HVAC unit is sitting on the slab and has not been hooked up. Is it covered?
Staging of equipment is a common gap in people’s assumptions. Some forms treat uninstalled equipment differently from equipment that has been set and secured. Ask where those items are covered — on site, in transit, or in storage — and at what limit.
Is a homeowners policy enough if I already own the lot in Dallas?
A homeowners policy is typically built for a completed, occupied house. A house under construction is more often reviewed as a builder’s risk placement. If an existing house is being remodeled rather than built new, both policies may need to be read together. Describe the work honestly.
Who buys the policy on a DFW custom home — the owner or the builder?
Either, or both, can appear, depending on the construction contract and the lender. The important part is that the people and firms with a financial interest are actually named, and that two policies, if they exist, are not assumed to be doing the same job. Confirm it on the issued form.
Talk with Peak Insurance
If you are building or remodeling in Dallas or elsewhere in the Metroplex, Peak Insurance can review these hail and storm questions with you before the frame goes up. Call 855-449-8552 or request a quote.
